

Which Pacific Life company pays you?
Pacific Life's structured settlement site lists two issuing companies:
- Pacific Life Insurance Company issues structured settlement annuities in every state except New York. Its home office is in Omaha, Nebraska.
- Pacific Life & Annuity Company issues them in New York.
Your contract also names an assignment company, the entity that took over the obligation to pay you when your case settled. In the New York court orders below it is Pacific Life & Annuity Services, Inc., and the orders refer to it and the issuer together as "Pacific Life."
Check your settlement agreement and annuity contract for the exact names and your contract number. You'll need them for every service request and for any sale. If the terms are confusing, see owner, payee and beneficiary explained.
How to contact Pacific Life
Pacific Life's structured settlement contact page lists:
| What you need | Contact |
|---|---|
| Changes and questions after the annuity is issued | (888) 728-5611, 8:30 a.m. to 5:00 p.m. Eastern |
| Fax | (402) 479-0102 |
| Online access | Log in at ssa.pacificlife.com |
| Help with your online profile | (877) 784-0622, option 3 |
Pacific Life's site also has forms for common changes, including a contract change request and a direct deposit form, and a guide explaining why to name a beneficiary. Ask the service team which form you need before you mail anything.
For a lender, landlord or court, request a letter that lists your remaining payments. See structured settlement income verification letters.
Can you sell Pacific Life structured settlement payments?
Yes, with a court's approval. Pacific Life pays the schedule set by your settlement. It does not buy payments back or pay them early. To get a lump sum, you sell some or all of your future payments to a structured settlement buyer.
The buyer files a petition under your state's structured settlement protection act. Pacific Life is notified and can appear. A judge decides whether the sale is fair and in your best interest. Once the order is signed, Pacific Life sends the sold payments to the buyer and keeps paying you the rest.
Buyers won't skip court. Without a qualified order they owe a 40% federal excise tax under 26 U.S.C. § 5891.
Real Pacific Life deals from court records
Here's what three buyers actually paid for Pacific Life payments, from published Brooklyn court orders.
| Order | Buyer | Payments sold | Cash to seller | Rate |
|---|---|---|---|---|
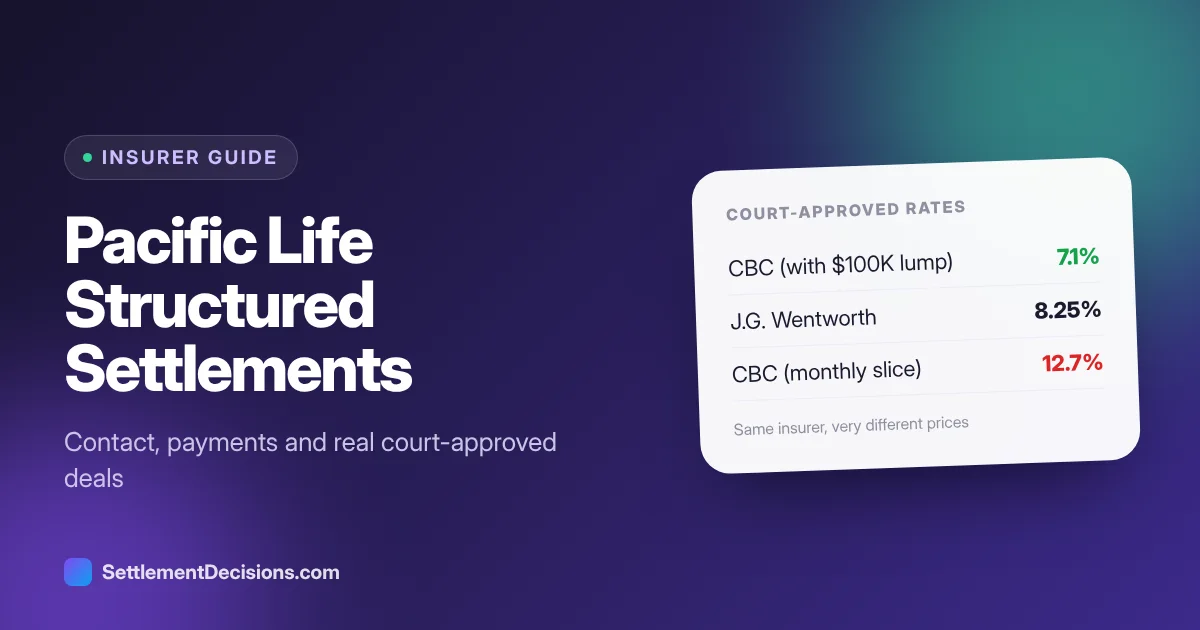
| Kings County, Apr. 23, 2021 | J.G. Wentworth | $700 a month for 6 months in 2021, then $1,063.92 a month from May 2026 to March 2032 ($80,102 total) | $45,000 | about 8.25% implied |
| Kings County, Mar. 30, 2021 | CBC Settlement Funding | $400 a month from 2020 to 2029, plus a $100,000 lump sum in July 2029 | not printed | 7.1% stated by the court |
| Kings County, 2020 | CBC Settlement Funding | $400 of each $1,402.07 monthly payment, May 2020 to July 2029 ($44,400 total) | $27,000 | about 12.7% implied |
"Implied" means the annual rate at which the payments sold are worth exactly the cash paid. It includes every fee, so it's the real cost of the deal. The 2020 order doesn't print its signing date, so we valued it from the first payment sold (May 1, 2020).
Three things stand out:
- Same insurer, very different prices. Rates ran from 7.1% to about 12.7%. The insurer's credit doesn't set your price; competition does.
- Lump sums often price better. The 7.1% deal included a $100,000 lump sum. Buyers like large, guaranteed lump sums from strong insurers.
- Partial sales are normal. In the 2020 deal the seller sold $400 of each monthly payment and kept about $1,000 a month.
Check your own offer against these and our other court records with the court deal benchmark.
How to get a fair price for Pacific Life payments
- Get your schedule in writing from Pacific Life, including any increases and lump sums.
- Sell only what you need. A share of each payment, or just the next few years, costs less than selling the whole stream.
- Ask at least three buyers for written offers on the same payments. Compare net cash and the effective annual rate.
- Run the numbers. Our discount rate calculator reverse-engineers the rate in any offer.
- Confirm the buyer is registered where required. See registered buyers by state.
- Prepare for the hearing. The judge will ask why you need the money now. See the court approval process.
Talk to a financial advisor who doesn't profit from the sale before you sign.
Pacific Life vs. other insurers
Pacific Life's own site describes "consistently high financial-strength ratings" and a nearly 160-year history. For a buyer, a strong insurer means less risk that payments stop, which can support a better price. For you, it's a reason to be sure you really need to sell. A guaranteed payment from a strong insurer is valuable to keep, too.
For how Pacific Life compares with MetLife, New York Life and others, see structured settlement rates by insurer.