

Which MetLife company pays your structured settlement?
"MetLife" on your check can mean more than one legal company, and the right name matters when you request letters, change your address or sell.
MetLife's annuitant page says structured settlement annuity contracts are issued by Metropolitan Life Insurance Company (MLIC), based at 200 Park Avenue in New York, or Metropolitan Tower Life Insurance Company (MTL), based in Lincoln, Nebraska. Both are wholly owned by MetLife, Inc.
Older contracts can carry other names. Court records show:
- MetLife Insurance Company of Connecticut as the insurer in a 2014 Manhattan case.
- Brighthouse Life Insurance Company as the issuer, with Metropolitan Life Insurance Company as the obligor, in a 2021 Brooklyn case.
Brighthouse Financial is the company MetLife separated its U.S. retail business into in 2017. If your paperwork says Brighthouse, your annuity may be issued by Brighthouse while MetLife still owes the payments. Your settlement agreement and annuity contract name the issuer (who holds the annuity) and the obligor or assignment company (who owes you). Write both down. See owner, payee and beneficiary explained if the terms are new.
How to contact MetLife about your payments
MetLife runs a dedicated line and portal for structured settlement recipients:
| What you need | How to get it |
|---|---|
| Phone | 1-800-638-2704, Monday to Friday, 8:00 a.m. to 9:00 p.m. ET |
| Online account | Log in to MyBenefits from MetLife's Structured Settlements Annuitant Center |
| Payment history and statements | In MyBenefits |
| Address or name change | In MyBenefits, or download the form from the annuitant center |
| Direct deposit | In MyBenefits, or on the direct deposit form |
Have your contract number, Social Security number and current address ready when you call.
If you need proof of income for a mortgage, apartment or car loan, ask MetLife for a letter listing your remaining payments. Our guide to structured settlement income verification letters explains what lenders look for. If a payment is late, see what to do about a missing payment.
Watch out for calls that sound like MetLife
MetLife's own annuitant page warns recipients about third parties offering cash for future payments. Those calls come from buyers, not from MetLife. A buyer can find you through public court filings, which is why calls often start after a case closes. If you weren't expecting the call, read why structured settlement companies keep calling you before you share anything.
Can you sell MetLife structured settlement payments?
Yes. MetLife does not buy payments back and will not cash out your annuity early. But you can sell some or all of your future payments to a structured settlement buyer if a court approves.
Every state has a structured settlement protection act. The buyer files a petition, MetLife is notified as an interested party, and a judge decides whether the sale is in your best interest. If a buyer completes a sale without a court order, it owes a 40% federal excise tax under 26 U.S.C. § 5891, so legitimate buyers don't skip this step.
Once the order is signed, MetLife redirects the sold payments to the buyer. You keep everything you didn't sell.
What you can usually sell:
- Guaranteed payments, which are paid no matter what. These get the best prices.
- Life-contingent payments, which stop when you die. Buyers pay much less for them and may require life insurance. See life-contingent payments explained.
- Part of a payment stream, such as the next five years, or a share of each check. See partial sales.
What buyers paid for MetLife payments in court
Buyers don't publish prices, but judges do. These are real New York court decisions involving MetLife payments, with the numbers taken from the orders.
| Case | Payments sold | Cash to seller | Rate | Result |
|---|---|---|---|---|
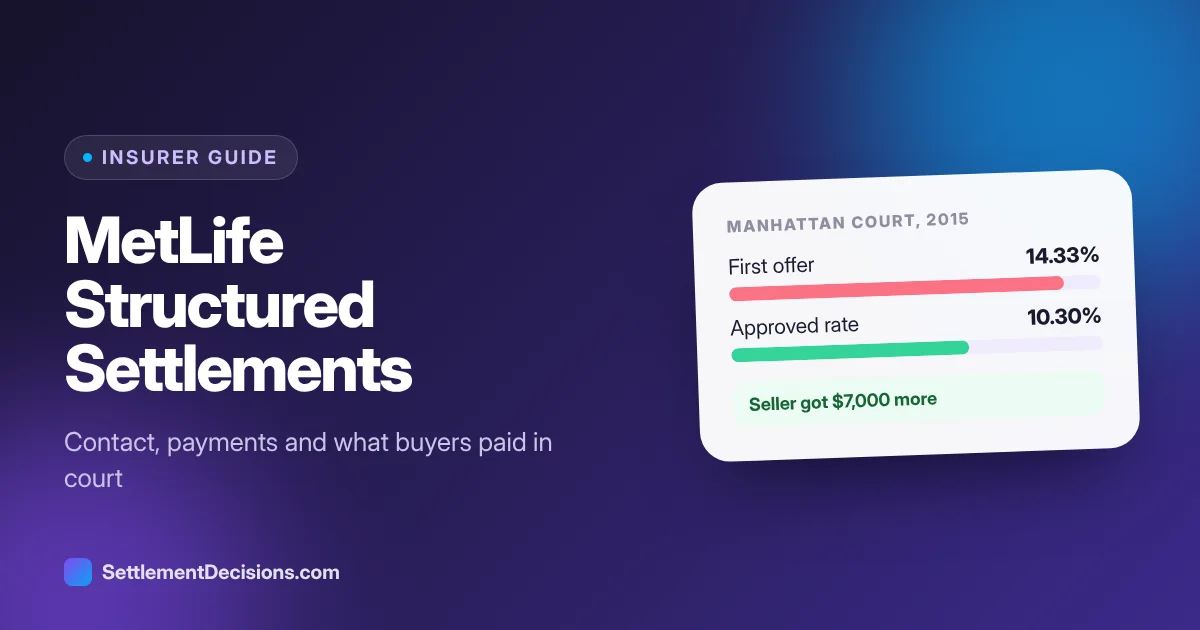
| J.G. Wentworth, NY County, Mar. 12, 2015 | 84 monthly payments of $900.41, rising 3% a year, 2015–2022 ($82,792 total) | $55,000 (raised from $48,000) | 14.33% → 10.30% | Approved |
| Peachtree, NY County, Nov. 17, 2014 | $25,000 in 2018 and $50,000 in 2023 ($75,000 total) | $45,300 (raised from $35,000) | 12.02% → 7.80% | Approved |
| Stone Street, NY County, June 20, 2014 | Monthly $378 payments to 2025 plus $45,000 (2016) and $55,000 (2026) | $85,100 (raised from $72,118.90) | 11.86% → 9.00% | Approved |
| PBX1 Chase, Kings County, Feb. 3, 2021 | Life-contingent monthly $6,014.76, rising 3% a year, 2046–2054 | $10,100 | about 15.4% implied | Approved |
The pattern is the useful part. In all three Manhattan cases, the first offer was raised before approval. The rates fell by 2.9 to 4.2 percentage points, and the sellers received between $7,000 and $13,000 more. Those increases came from the court process. You can get the same effect earlier by collecting competing written offers before anyone files a petition.
The 2021 case shows how buyers price life-contingent payments that start decades from now: $10,100 for payments that would total about $642,000 if the seller lives to receive them all.
Want to see where your own offer falls? Our court deal benchmark compares it with every deal in our court-record dataset.
How to sell MetLife payments without leaving money behind
- Get your exact payment schedule from MetLife. Ask for a letter listing every remaining payment, including increases. Buyers price from this.
- Decide how much you actually need. Selling a few years of payments, or a slice of each payment, usually costs less than selling everything.
- Collect at least three written offers for the same payments. Compare the net cash and the effective annual rate, not just the headline number. Our payout calculator shows what different rates mean in dollars.
- Check that the buyer is registered where your state requires it. See registered buyers by state.
- Read the disclosure statement. It must show the total payments sold, the discounted value, the fees and the net amount at least a few days before you sign.
- Go to the hearing prepared. Judges ask why you need the money and whether there's a cheaper option. See the court approval process.
Before you decide to sell, talk to a financial advisor who doesn't earn anything from the sale. A sale can't be undone once the court approves it.
MetLife or a buyer: who does what
| Task | MetLife | Structured settlement buyer |
|---|---|---|
| Sends your payments | Yes | No, until a court order redirects sold payments |
| Changes your address, direct deposit or name | Yes | No |
| Verification and payment-schedule letters | Yes | No |
| Buys your future payments | No | Yes |
| Files the court petition | No (MetLife is notified) | Yes |
| Changes your payment amounts or dates | No, the contract is fixed | Only for payments it buys |
If someone says they're "with MetLife" and offers you cash for your payments, hang up and call MetLife at the number above.